What do Visa and Mastercard do? An intro to card networks
Source: Hacker News ↗ (cross-verified by 2 outlets — full list below)
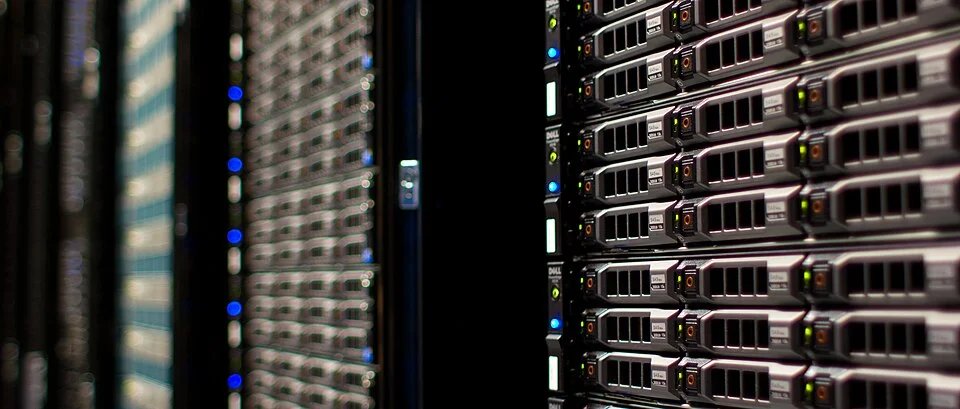
Visa and Mastercard operate as card networks that link card‑issuing banks and merchants’ acquiring banks, creating a two‑sided market for every payment transaction. When a consumer swipes or taps a card, the network forwards an authorization request from the merchant’s acquirer to the cardholder’s issuer, which then approves or declines the purchase. The network also handles the subsequent settlement process, moving funds between the issuer and acquirer after the transaction is finalized, and it performs net settlement each day to simplify the flow of money. Visa’s technical infrastructure consists of highly secure, redundant data centers—most notably its flagship Operations Center East in Ashburn, Virginia—where transaction messages are routed and protected against physical and cyber threats.
Beyond simply transmitting messages, the networks provide essential financial plumbing that enables both domestic and international payments. By maintaining relationships with banks worldwide, Visa can settle cross‑border transactions and manage currency conversion, sparing individual participants from establishing their own global banking connections. Card numbers function like IP addresses, with the first six to eight digits (the Bank Identification Number) identifying the issuing bank, allowing the network to direct requests accurately. Historically, these authorizations were handled manually via phone and mail, but modern networks automate the process, placing temporary holds on funds during authorization and later clearing the final amounts, such as added tips or voids.
The robustness of Visa’s data centers underscores the critical role of network reliability in the payments ecosystem; the facilities are fortified with biometric access controls, hydraulic bollards, and designs to withstand earthquakes and extreme winds. This physical security complements the network’s digital safeguards, ensuring uninterrupted service for millions of daily transactions. By acting as an adapter between disparate banking systems, the networks not only streamline everyday consumer purchases but also support the broader economy, enabling merchants of all sizes to accept cards and facilitating seamless international commerce without each party needing its own extensive banking infrastructure.
⚡ Effects Interpreter
🌍World Economylow impact
What this means for you
- ▶The ripples can spread across borders, nudging growth forecasts here and there.
- ▶Confidence among international firms might wobble until the picture clears.
🏙️Local Economylow impact
What this means for you
- ▶Neighbourhood traders usually adjust quietly rather than all at once.
- ▶Prices at your local shops could feel a soft, indirect squeeze from this.
🏦Rates & Banksmedium impact
What this means for you
- ▶Lenders often hold their nerve until a clearer trend appears.
- ▶Central bankers rarely rush; they prefer to see how the dust settles.
❤️Healthmedium impact
What this means for you
- ▶Worry has a way of spreading faster than the facts sometimes.
- ▶News like this can nibble at everyday calm more than people expect.
💷Wealthmedium impact
What this means for you
- ▶Nest eggs can wobble briefly before finding their footing again.
- ▶Your household's overall financial health matters more than any one day's numbers.
🏠Housinglow impact
What this means for you
- ▶Bricks and mortar tend to hold steady while other markets swing about.
- ▶Anyone selling soon might want a fresh valuation once the dust settles.
🌍 Effects for your country
The U.S.'s central bank rate currently stands at 3.75%, so a global rates move like this could feed through to local borrowing costs. The U.S.'s economy is growing at 2.3% with inflation at 3.2%, the backdrop this story's effects play out against locally. Housing-market effects like this are usually felt most where mortgage rates track the U.S.'s own central bank rate closely. With the U.S.'s unemployment at 4.4%, personal-finance effects like this land on a labour market that is currently fairly stable. Health-system effects are harder to localise from economic indicators alone — the real impact in the U.S. depends more on local healthcare capacity than the figures above.
The UK's central bank rate currently stands at 3.75%, so a global rates move like this could feed through to local borrowing costs. The UK's economy is growing at 0.8% with inflation at 3.2%, the backdrop this story's effects play out against locally. Housing-market effects like this are usually felt most where mortgage rates track the UK's own central bank rate closely. With the UK's unemployment at 5.6%, personal-finance effects like this land on a labour market that is currently fairly stable. Health-system effects are harder to localise from economic indicators alone — the real impact in the UK depends more on local healthcare capacity than the figures above.
France's central bank rate currently stands at 2%, so a global rates move like this could feed through to local borrowing costs. France's economy is growing at 0.9% with inflation at 1.8%, the backdrop this story's effects play out against locally. Housing-market effects like this are usually felt most where mortgage rates track France's own central bank rate closely. With France's unemployment at 7.9%, personal-finance effects like this land on a labour market that is already under strain. Health-system effects are harder to localise from economic indicators alone — the real impact in France depends more on local healthcare capacity than the figures above.
Romania's central bank rate currently stands at 6.5%, so a global rates move like this could feed through to local borrowing costs. Romania's economy is growing at 0.7% with inflation at 7.8%, the backdrop this story's effects play out against locally. Housing-market effects like this are usually felt most where mortgage rates track Romania's own central bank rate closely. With Romania's unemployment at 6%, personal-finance effects like this land on a labour market that is currently fairly stable. Health-system effects are harder to localise from economic indicators alone — the real impact in Romania depends more on local healthcare capacity than the figures above.
The UAE's central bank rate currently stands at 3.65%, so a global rates move like this could feed through to local borrowing costs. The UAE's economy is growing at 3.1% with inflation at 2.5%, the backdrop this story's effects play out against locally. Housing-market effects like this are usually felt most where mortgage rates track the UAE's own central bank rate closely. Health-system effects are harder to localise from economic indicators alone — the real impact in the UAE depends more on local healthcare capacity than the figures above.