Fall 2026 earnings watch
Source: The Verge ↗ (cross-verified by 2 outlets — full list below)
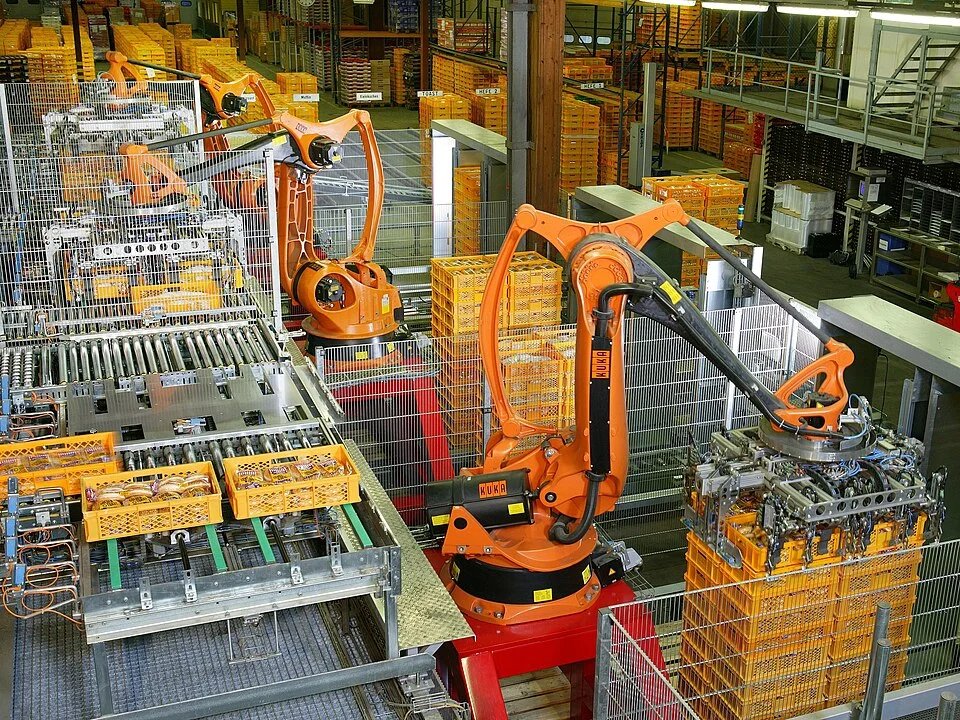
Tesla’s third‑quarter earnings are drawing attention not only for Elon Musk’s compensation incentives but also for the company’s ongoing development of humanoid robots, a venture that remains in the experimental stage as the firm seeks to make the machines useful, reliable and durable for consumers. The discussion of these topics surfaced during Meta’s third‑quarter earnings call, where CFO Susan Li remarked that “Everyone is just going to have to adapt,” underscoring the broader industry shift toward advanced robotics.
The emphasis on Tesla’s robot program highlights a strategic diversification beyond its core automotive business, reflecting the company’s ambition to pioneer a new market segment. However, the statement also signals the challenges Tesla faces in turning prototype technology into commercially viable products, a process that requires solving technical hurdles related to functionality, safety and long‑term durability before customers will adopt the devices.
Li’s comment, delivered in the context of Meta’s earnings briefing, suggests that the adaptation she references will affect multiple technology firms as artificial‑intelligence‑driven robotics become more prevalent. Stakeholders—including investors, suppliers and potential buyers—will be watching how Tesla resolves these development issues, which could influence competitive dynamics across both the automotive and robotics industries.
⚡ Effects Interpreter
🌍World Economymedium impact
What this means for you
- ▶The ripples can spread across borders, nudging growth forecasts here and there.
- ▶World markets have a habit of reading between the lines of stories like this.
🏙️Local Economylow impact
What this means for you
- ▶Slight businesses nearby might tweak their prices in the weeks ahead.
- ▶The pinch, if any, tends to show up first at the till.
🏦Rates & Banksmedium impact
What this means for you
- ▶Financial markets sometimes overreact to rate speculation before banks even respond.
- ▶A sudden leap in mortgage costs from this alone would be out of character for lenders.
❤️Healthmedium impact
What this means for you
- ▶Looking after mental health is worth it when headlines feel heavy.
- ▶The strain, if any, tends to show up quietly in everyday life.
💷Wealthlow impact
What this means for you
- ▶Your overall wealth picture is unlikely to be defined by a single story like this.
- ▶It's rarely wise to make big financial decisions purely on breaking news.
🏠Housingmedium impact
What this means for you
- ▶A slow-moving market like housing rarely reacts overnight.
- ▶A cooling or warming market usually takes months to fully show up in prices.
🌍 Effects for your country
The U.S.'s central bank rate currently stands at 3.75%, so a global rates move like this could feed through to local borrowing costs. The U.S.'s economy is growing at 2.3% with inflation at 3.2%, the backdrop this story's effects play out against locally. Housing-market effects like this are usually felt most where mortgage rates track the U.S.'s own central bank rate closely. With the U.S.'s unemployment at 4.4%, personal-finance effects like this land on a labour market that is currently fairly stable. Health-system effects are harder to localise from economic indicators alone — the real impact in the U.S. depends more on local healthcare capacity than the figures above.
The UK's central bank rate currently stands at 3.75%, so a global rates move like this could feed through to local borrowing costs. The UK's economy is growing at 0.8% with inflation at 3.2%, the backdrop this story's effects play out against locally. Housing-market effects like this are usually felt most where mortgage rates track the UK's own central bank rate closely. With the UK's unemployment at 5.6%, personal-finance effects like this land on a labour market that is currently fairly stable. Health-system effects are harder to localise from economic indicators alone — the real impact in the UK depends more on local healthcare capacity than the figures above.
France's central bank rate currently stands at 2%, so a global rates move like this could feed through to local borrowing costs. France's economy is growing at 0.9% with inflation at 1.8%, the backdrop this story's effects play out against locally. Housing-market effects like this are usually felt most where mortgage rates track France's own central bank rate closely. With France's unemployment at 7.9%, personal-finance effects like this land on a labour market that is already under strain. Health-system effects are harder to localise from economic indicators alone — the real impact in France depends more on local healthcare capacity than the figures above.
Romania's central bank rate currently stands at 6.5%, so a global rates move like this could feed through to local borrowing costs. Romania's economy is growing at 0.7% with inflation at 7.8%, the backdrop this story's effects play out against locally. Housing-market effects like this are usually felt most where mortgage rates track Romania's own central bank rate closely. With Romania's unemployment at 6%, personal-finance effects like this land on a labour market that is currently fairly stable. Health-system effects are harder to localise from economic indicators alone — the real impact in Romania depends more on local healthcare capacity than the figures above.
The UAE's central bank rate currently stands at 3.65%, so a global rates move like this could feed through to local borrowing costs. The UAE's economy is growing at 3.1% with inflation at 2.5%, the backdrop this story's effects play out against locally. Housing-market effects like this are usually felt most where mortgage rates track the UAE's own central bank rate closely. Health-system effects are harder to localise from economic indicators alone — the real impact in the UAE depends more on local healthcare capacity than the figures above.