Why the US midterms sparked an AI stock selloff
Source: BBC Business ↗ (cross-verified by 2 outlets — full list below)
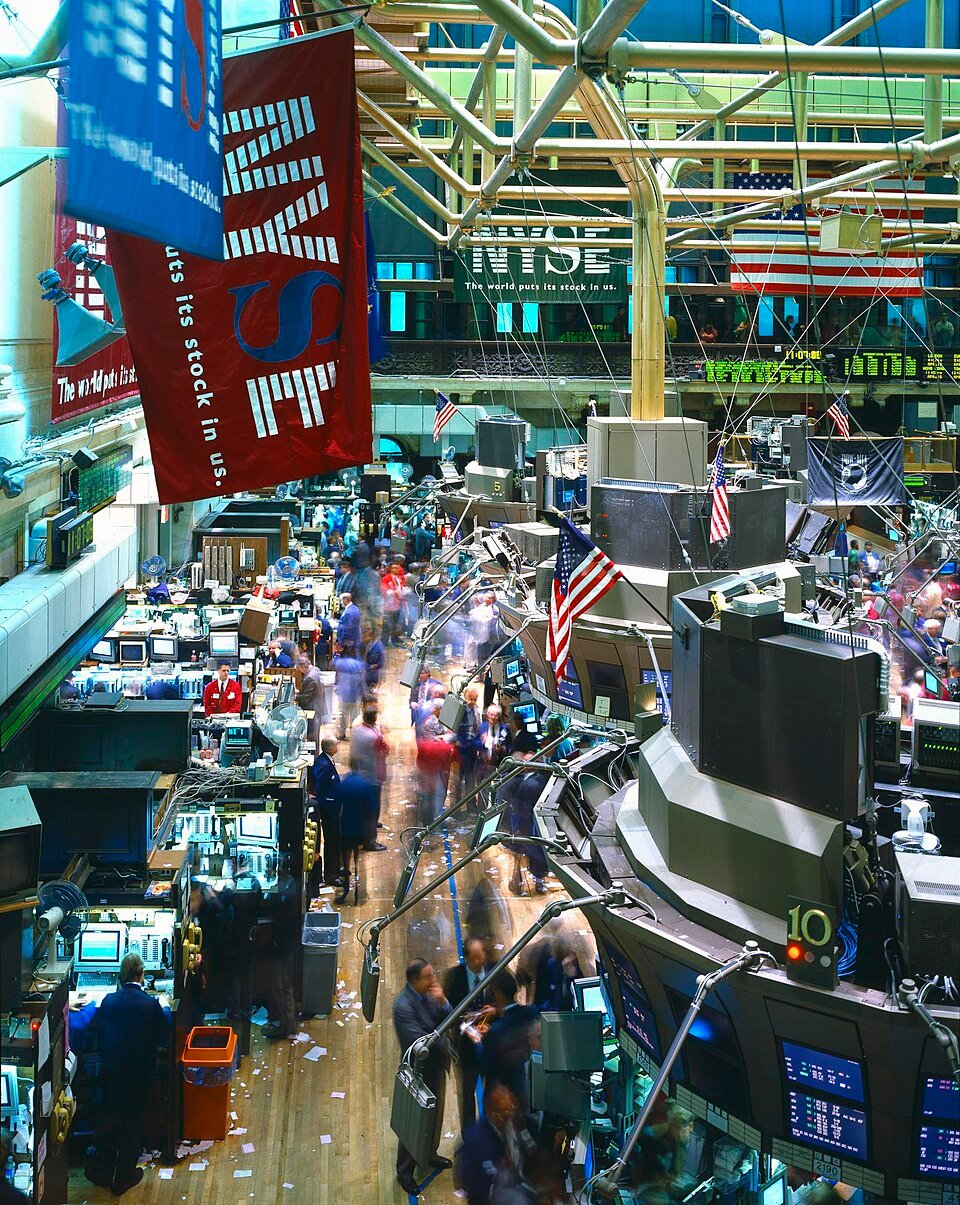
Investors dumped AI‑related stocks on Thursday after the U.S. midterm elections handed Democrats full control of Congress, sparking fears that the new majority will tighten regulation of the sector. The sell‑off was most pronounced on the Nasdaq, where giants such as Alphabet, Nvidia, Meta and Apple saw their shares plunge. The market reaction followed a wave of Democratic campaigning against the unchecked expansion of data centres, which power AI models, and a broader concern that future legislation could curb the industry’s growth.
The anxiety has been building since OpenAI’s ChatGPT launch in late 2022, which ignited a “gold rush” of capital into chip makers, networking firms, data‑centre operators and AI developers, driving tech valuations to record highs. Goldman Sachs projects AI‑related investments to reach $1 trillion by 2026, and the influx of money has pushed borrowing costs higher for other sectors. Yet recent public warnings from AI researchers about safety risks and the possibility of an existential threat have amplified speculation that regulators may intervene. A May Gallup poll showed 71 % of Americans would oppose a new data centre in their community—higher than opposition to nuclear plants—fueling political pressure on the industry.
Analysts say the midterm outcome may simply be pruning excess optimism rather than confirming a bubble about to burst. Tudor Brown of Arm Holdings notes that stock prices reflect future earnings expectations, and if those prospects dim investors will sell. Nandini Roy Choudhury of Future Market Insights expects traders to become more selective, favoring firms with solid balance sheets, while Brown predicts a “natural floor” will hold valuations because the sector still generates substantial revenue. The immediate outlook suggests a muted recovery for tech stocks, with the longer‑term impact hinging on whether Democrats enact restrictions on data‑centre construction, energy use and AI deployment.
⚡ Effects Interpreter
🌍World Economylow impact
What this means for you
- ▶Trade ties might tighten or loosen as the numbers sink in.
- ▶Currency desks typically move first, long before economists publish anything.
🏙️Local Economymedium impact
What this means for you
- ▶Your council tax and utility bills can indirectly track big economic swings.
- ▶Local firms typically watch national data before setting their own prices.
🏦Rates & Banksmedium impact
What this means for you
- ▶Rate-setters usually take their time digesting a story like this.
- ▶Base rate decisions are usually made on data trends, not single headlines.
❤️Healthlow impact
What this means for you
- ▶Neighbours and families might feel more anxious until the dust settles.
- ▶Community spirit typically steadies nerves when headlines feel unsettling.
💷Wealthmedium impact
What this means for you
- ▶Diversified savings usually cushion the blow from stories like this.
- ▶Checking in on your finances now and then is good practice regardless of headlines.
🏠Housinglow impact
What this means for you
- ▶First-time buyers watching the market closely may see little change in the short term.
- ▶Housing supply and demand rarely turn on a single piece of news.
📊 Country financial snapshot
United States
Source: IMF World Economic Outlook; each figure shows its year, and current-year values are IMF estimates. Policy rates and sovereign credit ratings are from the News Effects country dataset and show their own as-of date. Not investment advice.
🌍 Effects for your country
The U.S.'s central bank rate currently stands at 3.75%, so a global rates move like this could feed through to local borrowing costs. The U.S.'s economy is growing at 2.3% with inflation at 3.6%, the backdrop this story's effects play out against locally. Housing-market effects like this are usually felt most where mortgage rates track the U.S.'s own central bank rate closely. With the U.S.'s unemployment at 4.2%, personal-finance effects like this land on a labour market that is currently fairly stable. Health-system effects are harder to localise from economic indicators alone — the real impact in the U.S. depends more on local healthcare capacity than the figures above.
The UK's central bank rate currently stands at 3.75%, so a global rates move like this could feed through to local borrowing costs. The UK's economy is growing at 1.3% with inflation at 3.3%, the backdrop this story's effects play out against locally. Housing-market effects like this are usually felt most where mortgage rates track the UK's own central bank rate closely. With the UK's unemployment at 5.3%, personal-finance effects like this land on a labour market that is currently fairly stable. Health-system effects are harder to localise from economic indicators alone — the real impact in the UK depends more on local healthcare capacity than the figures above.
France's central bank rate currently stands at 2%, so a global rates move like this could feed through to local borrowing costs. France's economy is growing at 0.4% with inflation at 2.4%, the backdrop this story's effects play out against locally. Housing-market effects like this are usually felt most where mortgage rates track France's own central bank rate closely. With France's unemployment at 8.4%, personal-finance effects like this land on a labour market that is already under strain. Health-system effects are harder to localise from economic indicators alone — the real impact in France depends more on local healthcare capacity than the figures above.
Romania's central bank rate currently stands at 6.5%, so a global rates move like this could feed through to local borrowing costs. Romania's economy is growing at -0.5% with inflation at 8.2%, the backdrop this story's effects play out against locally. Housing-market effects like this are usually felt most where mortgage rates track Romania's own central bank rate closely. With Romania's unemployment at 6.5%, personal-finance effects like this land on a labour market that is currently fairly stable. Health-system effects are harder to localise from economic indicators alone — the real impact in Romania depends more on local healthcare capacity than the figures above.
The UAE's central bank rate currently stands at 3.65%, so a global rates move like this could feed through to local borrowing costs. The UAE's economy is growing at -3.9% with inflation at 4.5%, the backdrop this story's effects play out against locally. Housing-market effects like this are usually felt most where mortgage rates track the UAE's own central bank rate closely. Health-system effects are harder to localise from economic indicators alone — the real impact in the UAE depends more on local healthcare capacity than the figures above.